Moving from DC to Philadelphia, the change starts with your price frame. DC's median sale price is about $665,000 while Philadelphia's citywide median is about $279,000 (Redfin, three months ending September 2026), so the same money buys roughly 2.4 times the home, and a different kind of home: a fee-simple rowhouse instead of a condo. Verified November 2026.
I'm Craig Lerch, a broker at eXp Realty, and this is the comparison I run most with clients leaving DC: the price gap is the headline, but the housing stock and the tax mechanics are what actually reshape the search. This post is the DC-specific version of the move guide that already covers Boston, New York, and Texas.
The price gap, with receipts
Redfin's city pages put Washington at about $665,000 for the three months ending September 2026 (down about 1.5% from a year earlier) and Philadelphia at about $279,000 (up about 4.6%). Other trackers read the District lower: Stacker's 2026 median is $563,333 and Zillow's average DC home value is $566,961, so the honest range is roughly $560,000 to $665,000 depending on the source. Whatever tracker you use, DC's median lands at two to two-and-a-half times Philadelphia's (Redfin; Stacker; Zillow, verified November 2026).
The gap widens for the closer-in DC suburbs: Northern Virginia's median ran about $710,000 in August 2026 and Montgomery County, Maryland about $610,000 on Redfin's three-months-ending-September-2026 reading. A budget built for Arlington or Bethesda is a twice-the-city budget in Philadelphia, so stop thinking in DC price bands and start thinking in per-address tax math.
The housing stock is the real culture change
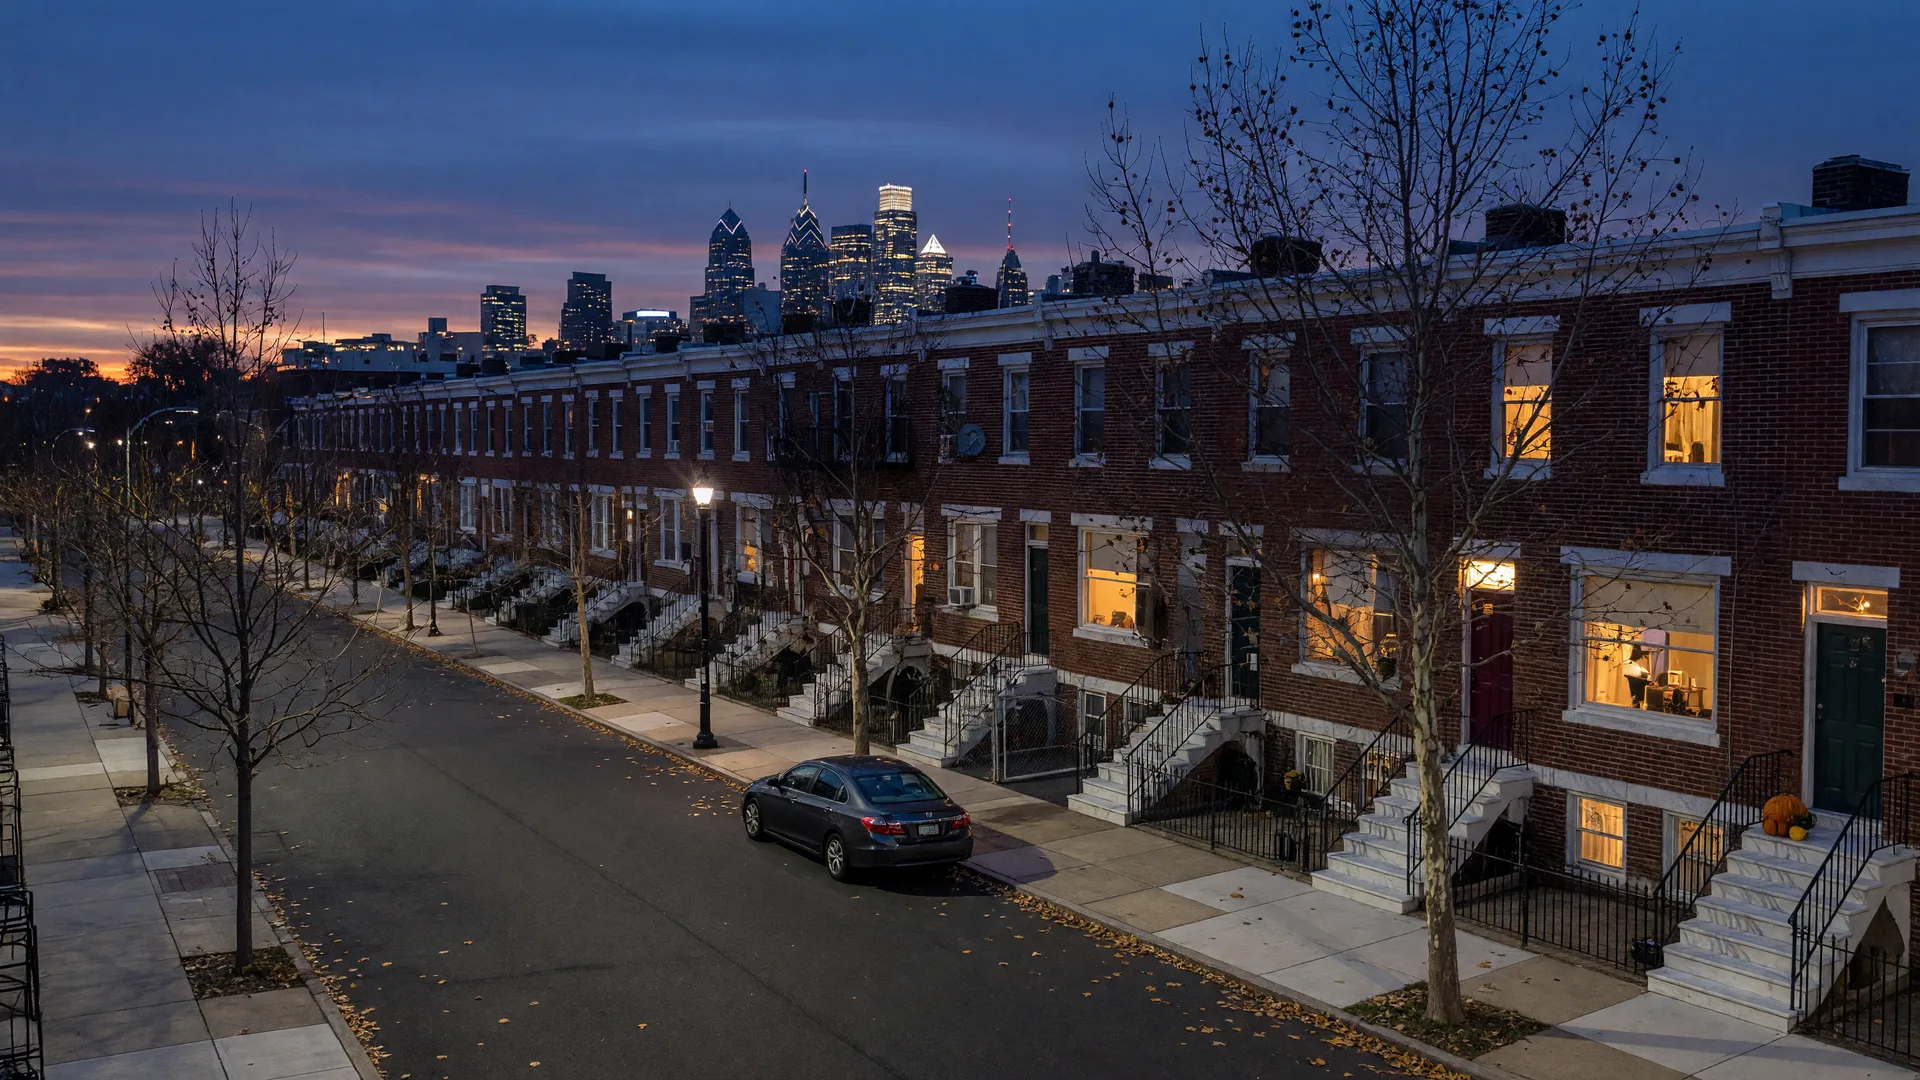
DC's roughly 304,000 housing units (D.C. Policy Center, Taking Stock) break down as: about 69,000 fee-simple rowhouses, under 25% of the stock; condos about 21%; co-ops about 8%; and a large rental base, which is why the single most common home in the District is the apartment building. Detached single-family houses are the smallest slice at roughly 11 to 13%. Philadelphia runs the opposite shape: about 55 to 56% of units are attached single-family rowhouses and only about 8% are detached (Census ACS, verified September 2026). The practical effect: a DC buyer searching for a house lands on a condo or a rowhouse; a Philadelphia buyer lands on a rowhouse with fee-simple ownership of the land, a party wall shared under the Philadelphia Building Code (section 706.1.1), and usually no condo board at all.
The blocks differ too. DC rowhouse streets hold parking mostly on the street under a zone permit system; many Philadelphia rowhouse blocks sit on rear alleys with small yards and off-street parking pads, exactly what relocating DC posters in r/AskPhilly and r/washingtondc threads flag as the change that makes keeping a car practical. The permit math: Philadelphia's Residential Permit Parking is a flat $75 a year per vehicle (verified September 2026); DC's is tiered at $55 for the first vehicle, $80 for the second, $115 for the third, and $175 beyond that, with zones capping non-permitted parking at two hours on weekdays (DC DMV, verified November 2026). Philadelphia's street-cleaning season, April through October with a $31 ticket (verified September 2026), is the other mechanic to learn.
Closing costs flip sides and get bigger
In DC, the deed recordation tax is the buyer's line item: 1.1% of the price below $400,000 and 1.45% on the full amount at $400,000 and above, while the seller pays the separate 1.45% transfer tax. First-time DC homebuyers can drop the recordation rate to 0.725% (DC Office of Tax and Revenue, verified November 2026). In Philadelphia, the Realty Transfer Tax is a combined 4.578% (3.578% city plus 1% state, the city share raised July 1, 2025), customarily split roughly evenly between buyer and seller (phila.gov, verified September 2026).
Two worked examples make the shift concrete. A $600,000 DC purchase puts about $8,700 of recordation tax on the buyer's side before anything else. A $350,000 Philadelphia purchase, split evenly, puts about $8,000 on each side of a roughly $16,000 combined tax. The Philadelphia split is negotiable in the offer, so the who-pays column belongs in every worksheet you write.
Annual property taxes: DC's effective rate is genuinely lower
DC taxes owner-occupied single-family homes, rowhouses, and condos at $0.85 per $100 of assessed value (0.85%), stepping to $1.00 per $100 above about $2.5 million, and the Homestead Deduction subtracts $91,950 from the assessment, saving a qualifying owner about $781 a year. Because DC assessments are capped below market value, the effective rate lands around 0.6% (DC OTR; Tax Foundation, verified November 2026).
Philadelphia's effective rate is about 0.83% with a $100,000 Homestead Exemption (verified September 2026), and the four surrounding counties run higher: roughly 1.30% in Chester, 1.31% in Bucks, 1.35% in Montgomery, and 1.84% in Delaware. New Jersey runs about 1.88% with the ANCHOR program; Delaware about 0.48%, with no wage-tax credit for Philadelphia workers. On the property line alone, DC is the cheaper seat; the income tax is where a DC-to-PA move usually saves.
Income taxes: a 10.75% top bracket has no Philadelphia analogue
DC runs a seven-bracket income tax that reaches 8.5% over $60,000, 9.25% over $250,000, and 10.75% over $1,000,000 (DC OTR, verified November 2026). Pennsylvania taxes wage income at a flat 3.07%, and Philadelphia layers on its Earnings Tax at 3.735% for residents and 3.425% for non-residents who work in the city (phila.gov, effective July 1, 2026). For a DC household the PA flat rate plus the wage tax is usually a net drop, but the wage tax is the part to plan around: it follows the job, not the address, and the telework rules in my wage tax guide decide where taxable days land.
The commute you keep: Amtrak, SEPTA, and the split-week calendar
A DC expat with a federal or agency role does not lose Washington. 30th Street Station to Union Station runs about 1 hour 35 minutes to 1 hour 45 minutes on Acela and about 1 hour 50 minutes to 2 hours 10 minutes on the Northeast Regional, with advance one-way fares from about $19 (Amtrak, verified October 2026). Door to door still runs about 2 to 2.5 hours, which is why hybrid schedules work better than daily commutes.
Inside Philadelphia, SEPTA's base fare is $2.90 with two free transfers within two hours (verified September 2026), against Metro's distance-and-time fares of $2.25 to $6.75 (verified October 2026). The full SEPTA-versus-Metro comparison is worth reading before you assume the two cities ride the same way.
Weather: same latitude, one honest difference
NOAA's 1991-2020 normals put Reagan National's January average high at 44.8 degrees Fahrenheit versus Philadelphia's 41.3, and July at 89.6 versus 87.8. The difference that changes behavior is snow: about 13.7 inches a year at Reagan against about 23.1 in Philadelphia (NOAA NCEI, verified November 2026). Same four seasons, roughly nine to ten more inches of snow, and the sidewalk-shoveling rules that come with it.
What most people get wrong
- A Philadelphia rowhouse is a cheaper DC rowhouse. The bones differ: fee-simple land with a shared party wall under the Building Code, no HOA or condo board for most of the stock, and new irredeemable ground rents banned since 1885 (verified September 2026). The blocks differ too: rear alleys and parking pads are common in Philadelphia in a way they are not in DC's rowhouse districts.
- Moving to Philadelphia means trading one condo for another. The default Philadelphia purchase is a fee-simple house, so the DC buyer used to board rules and maintenance fees takes on roof, boiler, and party-wall ownership instead.
- Historic-district rules vanish with the DC ZIP code. DC routes changes to rowhouses through its Historic Preservation Office and Review Board, with most work staff-approved under DC Code section 6-1105 (verified November 2026); Philadelphia has its own Historical Commission review in districts like Old City and Society Hill under Philadelphia Code section 14-2007 (verified September 2026). Check the district before you plan a renovation.
- Everything costs half as much. The price gap is real, but the wage tax, the 4.578% transfer tax, and county property rates from 1.30% to 1.84% narrow the monthly gap fast, and a CPA should run your exact numbers before the budget celebration.
The honest comparison is per address, not per city
A DC family is used to one county, one tax base, one assessor. Greater Philadelphia is a five-county market with a city wage tax, a city property rate, four suburban county rates, a New Jersey alternative, and a Delaware corner. The way to compare is to build a per-address sheet: purchase price, transfer tax split, annual property tax at that township's assessment rate, the wage tax if anyone in the household works in the city, and the commute to wherever the job actually is. Every candidate address should come with its own county's rate sheet, and a CPA should run the individual columns.
Your next step
Set aside an hour and build that sheet for three candidates: one Philadelphia rowhouse block, one rail-suburb township, and one wildcard. Then bring the sheet to a call so the gaps get closed with real listings and current rates.
Book a free relocation call and I'll turn your DC budget and commute into a Philadelphia criteria worksheet: the rowhouse blocks in range, the commute to 30th Street, and the per-address tax math. No follow-up required.
This is general information, not tax or legal advice. Have a CPA run the individual tax columns and an attorney review any contract. The rates and rules above were verified in November 2026 and can change, so confirm against current sources before you commit.
Related reading